
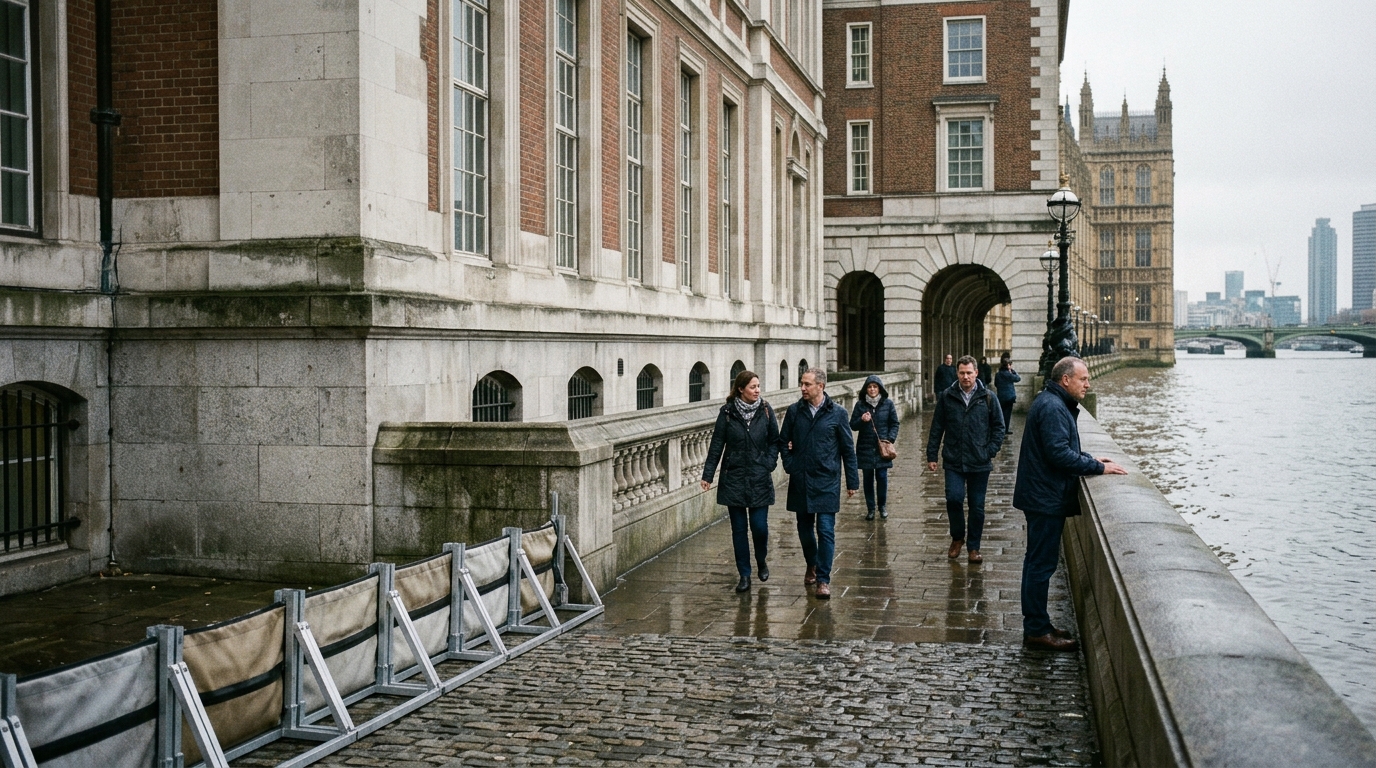

A national drive to standardise how homes measure, mitigate, and declare water risk has begun, mirroring the framework that transformed energy efficiency across British property over the past two decades. Under plans unveiled by the Department for Environment, Food and Rural Affairs alongside the reinsurance scheme Flood Re, ministers are piloting dedicated Flood Performance Certificates across England.
The system introduces a standardised rating framework designed to give prospective buyers, lenders, and insurers an unambiguous record of a building's flood vulnerability. Modelled explicitly on Energy Performance Certificates, these documents will break down a property's individual profile into specific tiers covering exposure, structural characteristics, and physical resistance measures.
For homeowners across river corridors and low-lying catchments, the policy shift marks a fundamental change in how vulnerability is quantified during a property transaction. Until now, buyers have leaned heavily on standard desk-based environmental searches. These searches indicate postcode-level likelihoods from surface water or rivers, but they rarely reflect individual mitigation work carried out on the ground.
Moving Beyond Postcode Lottery Assessments
The core friction in the current market lies between macro-level flood mapping and micro-level property resilience. A home sitting fifty metres from a riverbank might carry a daunting risk designation on paper, yet its owners may have invested thousands of pounds in non-return drainage valves, raised electrical sockets, and barrier systems. Under present conveyancing norms, that distinction often gets lost in the survey process, scuppering sales or driving insurance premiums beyond reasonable reach.
The newly unveiled Flood Performance Certificates aim to rectify that disparity. By combining existing information from the national Check Your Flood Risk service with verified individual building surveys, the certificates will formally record property-level measures. These include self-closing air bricks, flood-resilient kitchens, and temporary barrier fittings that prevent water ingress or minimise damage if water enters.
Speaking on the launch during Flood Action Week, Floods Minister Emma Hardy emphasised the necessity of reliable baseline information for families and communities. The government wants all households to understand their specific vulnerability and see a clear route toward cutting that risk. In Hardy's words, the certificates offer people the chance to access clear, trusted information in one place about the exposure their home faces, allowing them to take targeted steps to build resilience.
The Mechanics of the National Pilots
Work on testing the certificates begins this year across communities designated at elevated risk, with an expanding series of pilots scheduled to run throughout 2027 and beyond. The overarching aim, spearheaded by Flood Re, is to establish an accessible, app-based self-assessment process that eventually becomes standard practice throughout the English housing market.
The real economic prize for households lies in insurance underwriting. Flood Re's stated objective is for private insurers to formally integrate these certificates into their underwriting models. If an owner can demonstrate that structural resistance cut their damage recovery costs, underwriters will have an objective, verified basis to offer preferential terms rather than applying sweeping, postcode-wide exclusions.
This market mechanism mirrors the early years of energy certification, though with sharper financial consequences. An inefficient boiler merely leads to higher utility bills; an uninsurable home halts a mortgage application dead in its tracks. Standardising resilience certificates provides lenders with a clear metric to assess long-term collateral risk as climate patterns shift.
Local Realities in the Garden of England
Across Kent, where properties line historic rivers like the Medway, the Stour, and the Darent, flood risk is not an abstract concept. It is an everyday consideration for solicitors, surveyors, and buyers. Low-lying villages, reclaimed coastal marshes, and market towns have faced recurring bouts of surface-water flooding and river surges over successive wet winters.
In a county market where homes command high values, transparency around water management directly influences transaction timelines. Across fifty key areas across the county, average days on the market sit around 196 days, reflecting an environment where prospective buyers conduct extensive due diligence before committing their capital. Properties carrying unresolved flood questions routinely see transactions drag out or collapse during legal enquiries.
Standardised documentation cuts through that uncertainty. For a buyer looking at a period home near a tributary, seeing an official performance rating that details installed defences offers reassurance that generic catchment maps simply cannot deliver. Conversely, for vendors, investing in resilient fittings becomes a measurable asset that protects saleability rather than a hidden cost lost under floorboards.
Bridging the Gap Between Search and Sale
The introduction of Flood Performance Certificates will also alter conveyancing procedure. At present, when an environmental search flags potential surface-water or river exposure, solicitors advise purchasers to obtain specialised insurance quotes before exchange of contracts. If insurers demand excessive excesses, purchasers frequently attempt to renegotiate prices or withdraw entirely.
Under the proposed certificate framework, buyers and their conveyancers will see not just the hazard category, but the home's defensive baseline. If a property receives a modest rating because simple measures like air brick covers have not been installed, both parties can quantify the remedial expenditure during negotiations. The ambiguity that so often derails deals is replaced by an actionable checklist.
The success of the pilot scheme will rely heavily on industry adoption. Surveyor bodies and the wider valuation profession will need consistent methodologies to audit measures accurately. A self-closing air brick must be certified as properly installed and maintained to retain its validity, much as insulation or glazing warranties function today.
The Long View on Property Resilience
The arrival of Flood Performance Certificates indicates where property valuation is heading over the next decade. Buyers are no longer evaluating homes solely on square footage, architectural charm, and proximity to commuter stations. Climate adaptation, structural resistance, and environmental overheads have moved into primary decision-making criteria.
As Flood Re and government partners broaden the rollout through 2027, property owners in flood-prone districts would do well to treat resilience as an essential component of capital value. Properties that can prove their defensive credentials through formal certification will retain market confidence, while those that ignore water resilience risk falling behind in an increasingly cautious property market.