
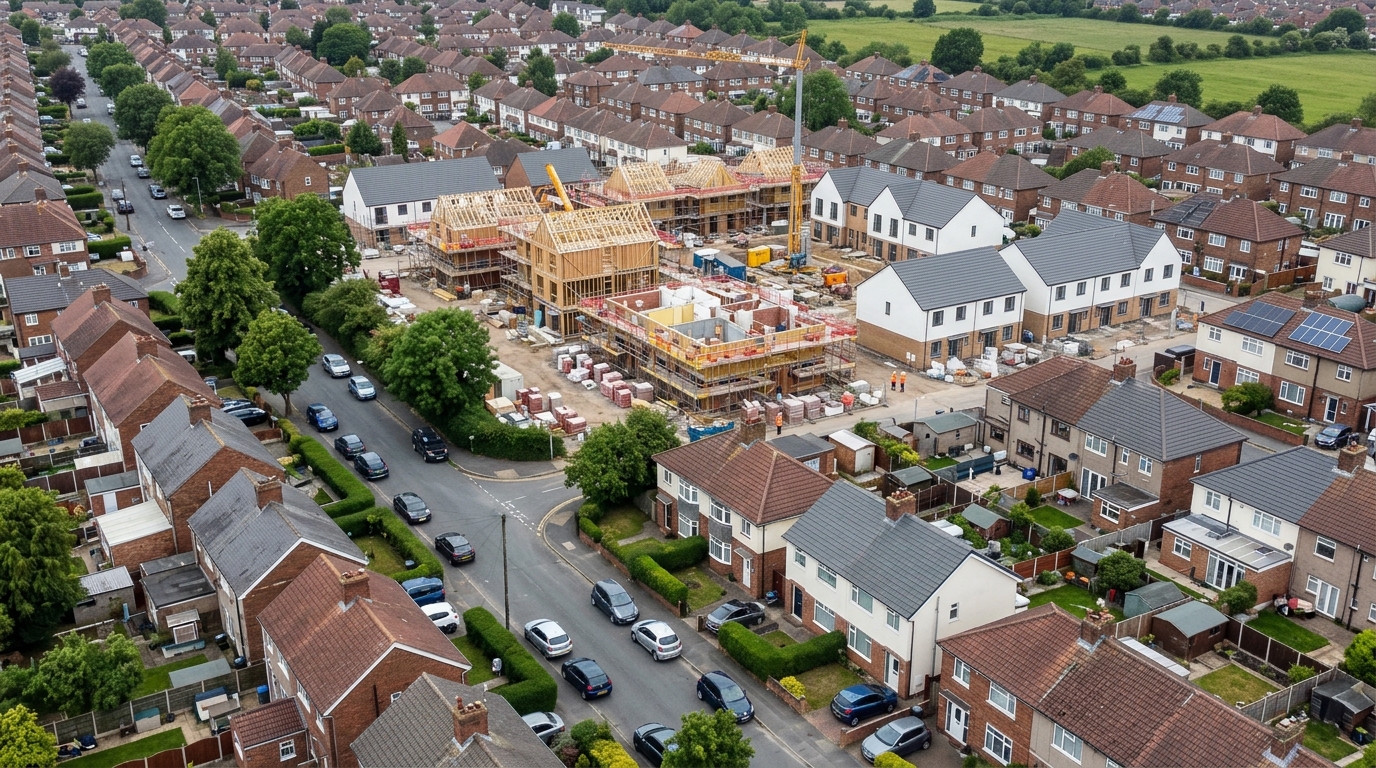

Housing and Planning Minister Matthew Pennycook has acknowledged that housebuilding in England faces acute viability pressures, speaking to sector leaders at the Housing Community Summit in Liverpool. Addressing delegates gathered by the National Housing Federation and the Chartered Institute of Housing, the minister conceded that delivery margins remain severely compressed by a sharp reduction in interest cover and elevated materials costs driven by global instability.
Viability Pressures Across the Tenures
The minister told delegates that housing associations and local authorities are grappling with a difficult balancing act: attempting to expand new social and affordable housing at scale while simultaneously financing significant safety and remediation works across existing properties. The remarks reflect challenges familiar to operators throughout the wider rental ecosystem. When development margins contract in the social sector, Section 106 agreements slow down, reducing the handover of affordable homes and intensifying competition across private lettings.
For the private rented sector, the implications are direct. Registered providers and institutional build-to-rent operators share identical financing and construction supply chains with smaller developers. When high debt costs curb housing association starts, municipal waiting lists lengthen. That structural shortfall routes more households directly into private tenancies, sustaining demand even as broader economic conditions squeeze family budgets.
Regional Realities Across Kent
Across Kent, these viability hurdles are visible on the ground. In commuter hubs such as Tonbridge, Tunbridge Wells, and Sevenoaks, planning permissions regularly stall over viability reassessments and Section 106 contributions. Housing associations operating across west and mid Kent have had to reallocate significant capital toward fire safety and decarbonisation, dampening their appetite for speculative land purchases or large-scale s106 acquisitions from volume housebuilders.
This ongoing supply pinch concentrates tenant demand in established rental stock. In Tonbridge and surrounding rail corridors, two-bedroom flats and family terraced houses experience persistent competition among applicants. Tenants who might historically have transitioned into intermediate tenures or shared ownership are remaining in private rented homes for longer periods. For local buy-to-let investors, void periods remain historically low, though landlords face their own balancing act between servicing mortgage debt and funding regular maintenance.
Decency Demands and Asset Management
A central theme of the minister's address was the dual burden placed on social landlords to build new units while lifting the decency of existing stock. That policy priority mirrors legislative changes advancing through Parliament for private lettings. The extension of the Decent Homes Standard and Awaab's Law to the private rented sector means individual landlords now operate under compliance frameworks comparable to those of major registered providers.
Meeting tighter compliance thresholds requires clear, multi-year asset management. Landlords holding older Victorian or Edwardian housing stock across Kentish towns must plan capital expenditure carefully, tackling damp, ventilation, and thermal efficiency before statutory deadlines harden. As the minister indicated in Liverpool, improving the safety and quality of homes is non-negotiable for government, regardless of construction cost inflation.
Financing Pressures and Future Supply
Pennycook highlighted that reduced interest cover has restricted borrowing capacity across the social housing sector. Private buy-to-let landlords have experienced an identical dynamic under higher base rates, where stringent interest coverage ratios have curtailed leveraged acquisitions. Portfolio landlords across the South East are increasingly prioritising debt consolidation, modest deleveraging, and targeted refurbishment over unhedged portfolio expansion.
The convergence of constraints across both social and private landlords indicates that the wider English housing shortfall will not clear quickly. Until construction costs stabilise and long-term borrowing rates ease, rental stock additions will struggle to match demographic demand across Kent's key commuter catchments. Landlords who invest systematically in the condition of their properties, maintain realistic rental yields, and foster long-term tenant stability will remain best placed to weather the prevailing structural constraints.